
- Individuals & Families
- Businesses
- Agents & Brokers
- Embedded Insurance

Protect your ring with Chubb Valuable Articles insurance and get the peace of mind and financial security you need.

Because pets are family, Chubb now offers pet insurance with top-rated coverage from Healthy Paws.

Chubb offers the insurance protection you need for travel’s many “what ifs”.

Recognized for Outstanding Customer Satisfaction among Small Business Insurers and ranked #1 in Digital Channels.

Stay ahead of cyber threats with our free Cyber Claims Landscape Report.

Learn more about our dedicated learning paths, Online Learning Center, and more.

Many digital-savvy consumers look for it as a core or add-on option.
Many digital-savvy consumers look for it as a core or add-on option.
Many digital-savvy consumers look for it as a core or add-on option.

Chubb’s in-house technology makes it easy to integrate what we do into your customer experience.

Every cherished home is unique—a place filled with personal possessions and memories that add meaning and value. And each home needs the right coverage to provide peace of mind and protection from disasters, accidents, and liability.
For millions of households, standard homeowners policies can provide sufficient coverage. But top tier homes—those built with premium materials, fine finishes, and handcrafted details—may need additional coverages, provided by specialized high value home insurance. If you own a large, upscale home—especially in areas with high construction costs—you may need luxury homeowners coverage.
What qualifies as a high value home
High value homes are typically more expensive to restore or rebuild after a catastrophic accident or natural disaster. Compared with standard home insurance, high value home insurance typically offers higher coverage limits, along with additional coverages designed to restore a home to its original quality using comparable materials and finishes. For example, high value home insurance may be needed for homes that typically exceed $1 million to rebuild in the event of a total loss, with the specific threshold varying by insurer.
Older, historic homes may have high rebuilding costs because classic molding, hardwood built-ins, stained glass, and other features are costly to replace. In addition, older plumbing and electrical systems may have to be upgraded to code when an older home is rebuilt.
On the other hand, newer homes with professional-grade appliances, custom tilework, home theaters, and other premium features are also expensive to rebuild. Larger, custom homes built with these high-quality materials and finishes likely require high value homeowners insurance as well.
Where standard homeowners insurance may fall short for high net-worth homeowners
Standard homeowners insurance typically provides coverage based on a general estimate of rebuilding costs, which will often leave luxury homes underinsured. A high value home policy will have higher limits that provide coverage for premium building materials and belongings.
Standard policies may also fall short when it comes to value-added services that often accompany luxury home insurance. High value home coverage may include a home assessment, loss prevention consulting, and more responsive claim services.
What do insurance policies for luxury homes cover?
At the most basic level, insurance for luxury homes will offer greater coverage than a standard homeowners policy. These policies provide coverage for:
Dwelling and reconstruction costs
A luxury home policy will provide coverage for materials and construction necessary to repair or replace the damaged home that added together may exceed the market value of your home. High value home policies may also provide extended replacement cost coverage, which will cover repair and rebuilding costs to restore your home to its original condition even if costs exceed your policy limit.
Personal property and valuables
Compared to a standard homeowners policy, a high value home policy will provide greater coverage for a range of personal property and valuables, including furniture, silverware, and some collectibles. Keep in mind, however, that homeowners policies may provide only limited coverage for especially valuable possessions such as fine art, antiques, jewelry, wine and spirits, and other collectibles. For higher value possessions and collections, you may need additional special coverage, such as a Chubb Valuable Articles policy.
Loss of use
Standard policies have tight limits on coverage for additional living expenses, which pays temporary housing costs when your home is temporarily unhabitable. A high value home policy will help pay for comparable housing while your home is being rebuilt or repaired. Chubb helps clients find a comparable home or hotel in their neighborhood or school district (when that is a concern), if possible.
High value home insurance policies may also provide the option of a cash settlement up to your policy’s limit in the event of a covered total loss, if you decide not to rebuild on the same property or if you opt to rebuild at another location. A cash payment from a standard policy may not be an option at the time of loss or it may be lower than the actual cost to replace the home.
How much does high value homeowners insurance cost?
Policy costs can vary widely based on a number of factors, including your home’s location and risk, its characteristics, coverage details, and your policy history. Insurers may offer additional discounts if you bundle other policies, such as auto or collectibles insurance. Features such as security and water leak detection systems may also help reduce your premium by qualifying you for a discount.
How to choose the right luxury home insurance policy for you
As a first step, reach out to an independent insurance agent or broker in your area who specializes in high value home insurance.
Your agent or broker will work with you to understand your priorities and can obtain quotes from multiple insurers customized to your needs. Before providing an exact quote, luxury home insurance carriers may conduct a home assessment to evaluate your property and determine risks. Your insurer may also want to appraise fine art, antiques, and other valuables in the home.
Some insurers will also provide risk consulting services to help you prevent damage to your home. If you add upgrades such as home security, leak detection systems, and resilient building materials, you may be able to receive credits that reduce your premium.
To get started, click here to find an agent in your area and get a quote.
Insights and expertise
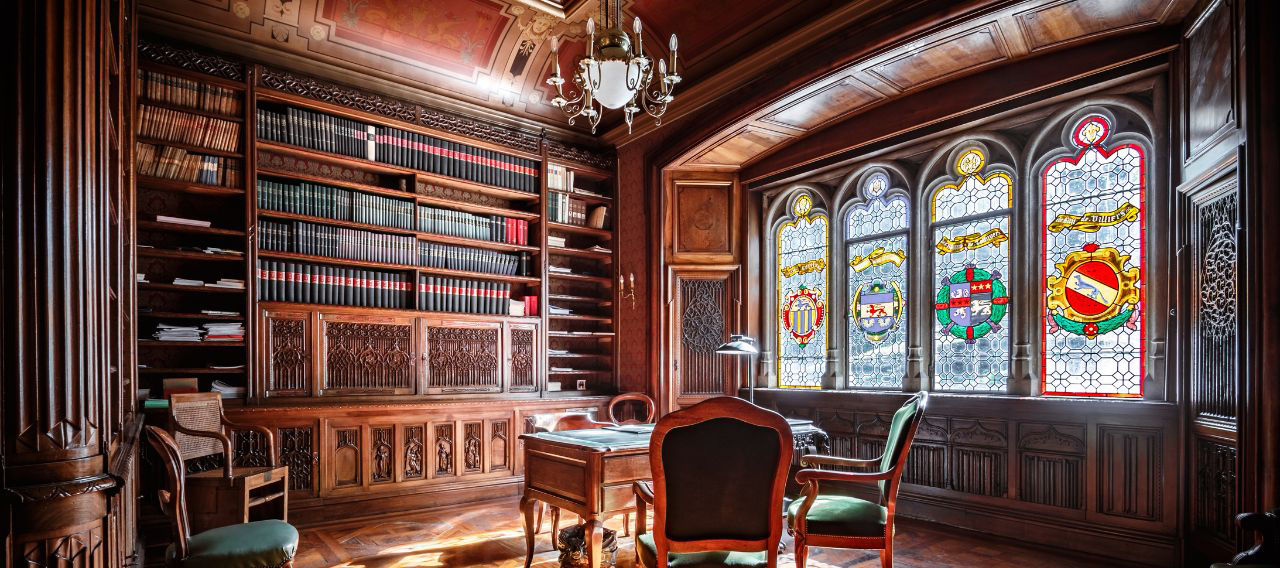
A guide to homeowners insurance for older or historic homes
Vacant but protected: Tips for safeguarding vacant homes
Protect your home from wind and wind-driven rain
Protecting your family and home from a flood
This document is advisory in nature and is offered as a resource to be used together with your professional insurance advisors in maintaining a loss prevention program. It is an overview only, and is not intended as a substitute for consultation with your insurance broker, or for legal, engineering or other professional advice.
Chubb is the marketing name used to refer to subsidiaries of Chubb Limited providing insurance and related services. For a list of these subsidiaries, please visit our website at www.chubb.com. Insurance provided by ACE American Insurance Company and its U.S. based Chubb underwriting company affiliates. All products may not be available in all states. This communication contains product summaries only. Coverage is subject to the language of the policies as actually issued. Surplus lines insurance sold only through licensed surplus lines producers. Chubb, 202 Hall's Mill Road, Whitehouse Station, NJ 08889-1600.