
- Individuals & Families
- Businesses
- Brokers
From your home and valuables, to prized collections and jewellery, you have a lot to insure. When you insure your home and contents with Chubb, you will receive a high level of service from an insurer who is specialised in working with successful individuals with high value assets.

For professionals in their first luxury apartment, villa or townhouse through to retirees downsizing from a family house, Masterpiece is also ideal for owners and tenants living in luxury apartments, villas and townhouses.

From high-value homes and fine art collections to luxury vehicles and more, we are here to help ensure that what you treasure most is treated with expertise.
With more than 25 years of experience providing travel insurance to Australians, Chubb Leisure Travel Insurance can help protect you and your family while you travel overseas, knowing Chubb support is there if an incident occurs.

Chubb leverages superior underwriting expertise and world renowned claims, account services, and financial strength to offer insurance solutions for small and medium businesses.

Today's multinational organizations face complex and interconnected risks. We offer insurance solutions that are tailored to global needs as well as local requirements, helping them address their risk challenges.
Our broker resources centre provides you with the latest updates, insights, sales tools, training and much more.
From a general perspective, the widely held opinion of many observers is that catastrophe events are becoming more frequent and severe. Climate change is the one single factor believed most to blame. Here we’ll consider and expand on that suggestion, look at the experience of the catastrophe teams at Chubb Overseas General (COG) and explore some of today’s major discussion points in catastrophe insurance.
COG operates a very diverse book of business and is discriminating in its risk appetite. For that reason, the exposure that Chubb has in one country, region or area may be very different to that which it has in another. A hailstorm on Australia’s east coast will generate a very different cohort of losses to an earthquake in Korea or a flood in Chile. Additionally, catastrophes are generally unpredictable. That all being considered, we have to be cautious when presented with statistics quoting average claim values or similar statistical measures because so much depends on the underlying risk portfolio. Despite this, there can be great value in looking at trend and experience as signposts to the future.
The National Oceanic and Atmospheric Administration (aka the National Hurricane Centre - a US government scientific agency) has named storms since the early 1950s, but it is perhaps no coincidence that 2020 saw 30 named events, a record for a single year. The previous record had been set in 2005 (28 storms) and prior to that, the record was 19 (1995, 2010, 2011, 2012). One can find similar statistics for bushfires in Australia and other seasonal catastrophe scenarios.
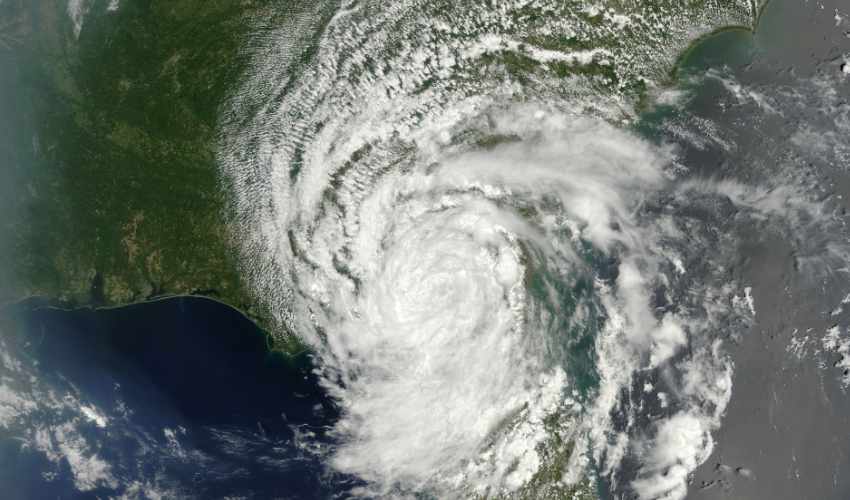
Looking broadly at in excess of 11,000 catastrophe losses or 43 catastrophe events registered by COG in 2020, many points stand out. First is an increase in the number of events that are reaching COG’s catastrophe threshold on an annual basis. Even considering a period of extremely recent history, the 43 events in 2020 compare to an average of 25 for the three preceding years and 18 for the five years before that.
Second, through our claims experience, we see that it is vital to contemplate the risk from natural perils in its widest sense, even in areas which may traditionally have been considered benign. To illustrate the point, we can choose between wildfires in Sweden in 2018, cyclone Idai which hit Mozambique in 2019, or to the present-day, extreme weather which plunged much of Texas into a prolonged freeze in 2021. None of these events could be considered normal for the territories in which they occurred, certainly at the severity witnessed. We will continue to see unusual things happening in unexpected places.
Place and location themselves raise an interest point if we ask whether the true issue at hand is nature impinging on humanity or humanity moving further into nature? According to the World Population Review, Mumbai’s population grew seven-fold between 1950 and 2020. For Sydney, much of which was impacted by the 2019/2020 bushfires, the increase is ten-fold with the population now estimated at 5 million. Population increase pushes urban boundaries further into nature’s path and brings with it all the dangers which previously appeared remote. We can apply this analysis equally to development on floodplains and the use of land reclaimed from the sea.
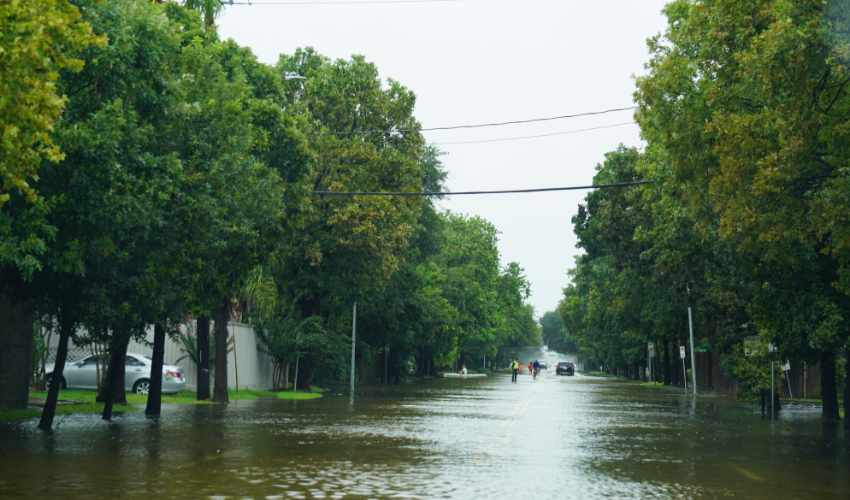
We also see that understanding the risk to a business involves more than understanding the risk to the property or location from which that business operates. As fire, hurricane and flood events increase in both frequency and severity, they threaten businesses not just through physical damage to insured property but by denying access to key locations and by damaging infrastructure and the properties of employees, customers and suppliers. In a world where a mobile phone draws components from over 200 suppliers, the focus on insurance risk must be global.
This serves to highlight the need for the insurance buyer to be discerning in the purchase of their coverage, not only to guarantee that they benefit from the appropriate breadth of peril-based coverage, but also to ensure that the policies dovetail together without leaving gaps or uncertainties.
Insights and Expertise
Reduced occupancy arson and malicious damage control
4 technologies to improve workplace safety
5 keys to driving business success
What businesses should know about water damage
Protecting employees during the COVID-19 pandemic
6 steps to prepare your business facilities for reopening
This content is brought to you by Chubb Insurance Australia Limited (“Chubb”) as a convenience to readers and is not intended to constitute advice (professional or otherwise) or recommendations upon which a reader may rely. Any references to insurance cover are general in nature only and may not suit your particular circumstances. Chubb does not take into account your personal objectives, financial situation or needs and any insurance cover referred to is subject to the terms, conditions and exclusions set out in the relevant policy wording. Please obtain and read carefully the relevant insurance policy before deciding to acquire any insurance product. A policy wording can be obtained at www.chubb.com/au, through your broker or by contacting any of the Chubb offices. Chubb makes no warranty or guarantee about the accuracy, completeness, or adequacy of the content. Readers relying on any content do so at their own risk. It is the responsibility of the reader to evaluate the quality and accuracy of the content. Reference in this content (if any) to any specific commercial product, process, or service, and links from this content to other third party websites, do not constitute or imply an endorsement or recommendation by Chubb and shall not be used for advertising or service/product endorsement purposes. ©2026 Chubb Insurance Australia Limited ABN: 23 001 642 020 AFSL: 239687. Chubb®, its logos, and Chubb.Insured.SM are protected trademarks of Chubb.